
Statement of Activities: Reading a Nonprofit Income Statement

The assets and liabilities listed on a 5 Main Benefits of Accounting Services for Nonprofit Organizations nonprofit’s Statement of Financial Position are listed as of a certain date, typically the end of the prior month or year-end. Nonprofits are unique because the focus is on accountability, not profitability. Financial statements are one of the most important tools that the leaders of a nonprofit organization can use to ensure the future health of the entity.

Free Resources

When in doubt, please consult your lawyer tax, or compliance professional for counsel. Sage makes no representations or warranties of any kind, express or implied, about the completeness or accuracy of this article and related content. Of course, not every nonprofit relies so heavily on donated goods or in-kind donations. Form 990 does not have to adhere to GAAP standards and contains additional information which, while relevant to the IRS, may be confusing for many of your stakeholders. The primary purpose of the statement of activities is to satisfy regulatory requirements, such as Generally Accepted Accounting Principles (GAAP) and Form 990 for the IRS.
- This statement should also clarify whether certain revenue sources and expenses are subject to any donor restrictions.
- Generally, nonprofits will report all their revenue into two categories – without donor restrictions and with donor restrictions.
- This, along with your net assets and change in assets, should be included in and clearly identified in your report.
- However, that does not mean that a nonprofit has no responsibilities whatsoever related to taxes.
- The Statement of Cash Flows provides a clear picture of your nonprofit’s liquidity and ability to cover expenses.
Improved Financial Management
- A formal statement of cash flows is different from daily cash management reports or cash forecasts because it separates the movement of cash into three categories.
- Examples include rent, utilities, office supplies, salaries of non-program staff, and professional fees.
- While each financial statement provides unique insights, they complement one another to give nonprofits a full picture of their financial situation.
- One of the things you need to do when you’re running a nonprofit organization is to keep track of your financial statements.
- The report reflects the changes to an organization’s net assets resulting from financial activities that occurred during the fiscal year.
- Since nonprofit financial statements differ from traditional financial reports, we’ve put together this simple guide to reading those essential statements.
- It is important to see the distinction between restricted and unrestricted as only unrestricted revenue can be used to pay bills.
These conditions might include performance-related metrics or specific project milestones. Until these conditions are satisfied, the funds are recorded as liabilities rather than revenue. This approach ensures that the organization does not prematurely recognize revenue that it may ultimately have to return if the conditions are not met. Be sure to pay attention to the net assets available to your organization under the “without restrictions” column of your statement of activities when analyzing the document for sustainability.

AccountingTools
Grant income comes from funds given by government agencies, foundations, other nonprofits, or grant-making entities. This transparency and detailed accounting https://greatercollinwood.org/main-benefits-of-accounting-services-for-nonprofit-organizations/ are vital for maintaining trust with donors, fulfilling regulatory requirements, and guiding strategic financial decisions. You should review your statement of activities monthly to identify trends and changes. If your organization has deficits in specific periods, those deficits should be offset by surpluses in other periods.
This practical example and template will help you better understand how the information discussed earlier comes together in a real-life document. If you’re unsure how to make these distinctions, check out this post on the difference between restricted and unrestricted funding. Websites like GuideStar also show a nonprofit’s Statement of Activities and use these details to award seals of approval. For instance, if you have a donor that wants to donate to school technology, your report must show that.

The statement of financial position has applications for both short- and long-term financial planning. Analyzing your statement of financial position and comparing it to reports from past years can show you whether your organization is on a positive trajectory for growth. Since it is similar to an income statement it has revenues, expenses and a change in net assets.
- This distinction helps organizations track and report how they are meeting donor expectations, ensuring transparency in how funds are allocated and spent.
- This calculation shows the equity of your nonprofit organization and whether you have the revenue to cover expenses, creating a sustainable organization.
- They do need to show how they are using their revenues and expenses to achieve their mission.
- Your net assets can be from the current and previous operating years and include anything that holds value.
Search form
A deficit, meanwhile, suggests there may need to be a hunt for new sources of funding or a reduction in costs. However, not all surpluses need to be spent— a prudent nonprofit can save them away for the proverbial rainy day. It’s also important to note that some assets may have more liquidity than others, which is good to keep track of in case of an emergency. Out of the four most common financial statements in a nonprofit, the Statement of Activities, also known as the Profit & Loss (P&L), is the broadest.
Battalion Oil Corporation Announces Fourth Quarter 2024 Financial and Operating Results
This is often confused with financing activities, so I want to emphasize this distinction.Finally, there are financing activities. Financing activities are related to the process of raising capital for the company or returning funds to stakeholders. In other words, financing activities refer to how a company obtains the funds necessary for its operations or investments. This includes a range of activities such as borrowing money from a bank, issuing bonds or stocks, paying interest, and distributing dividends.Then, how do these three activities generally interact with each other? To start a business, you would borrow money or make an investment to secure cash. Then, with that money, the manager would use it for operations or internal vs external financial reporting investment activities.
- You handle (or outsource) all the operational responsibilities, from financing to leasing and property management.
- The 1031 exchange can be a powerful tool when investing in commercial real estate, enabling tax deferral and compounding capital.
- Alternatively, the indirect method starts with net income from the income statement and adjusts it for non-cash items and changes in working capital to arrive at cash flow from operations.
- A rigorous due diligence process is essential in investing in commercial real estate, helping uncover hidden issues and validate financial projections.
- Distinguishing between “market value” and “investment value” is key to smart deal-making.
- By combining disciplined financial analysis, proactive management, and strategic planning, investors can navigate CRE’s complexities and leverage its unique strengths for sustained, long-term wealth creation.
These case studies highlight how different companies manage their cash flows in line with their strategic objectives, operational needs, and market dynamics. The analysis of their cash flow statements provides insights into their financial health, investment priorities, and shareholder value strategies. The nature of investing cash flows is such that they often result in negative figures on the cash flow statement, indicating that a company is investing in its future growth by spending money on capital assets.
Operating Cash Flow vs. Free Cash Flow
Commercial real estate offers distinct tax advantages that can significantly improve after-tax income. One of the most compelling aspects of commercial real estate investing is the array of tax benefits—from depreciation to 1031 exchanges—that can optimize returns. Borrowing can amplify both gains and losses when investing in commercial real estate.
- This model can also include owner-occupied real estate, where your own business is the primary tenant.
- Excluding the impact of hedges, Battalion realized 96.9% of the average NYMEX oil price during the fourth quarter of 2024.
- Understanding the nuances of cash flows and their interrelations will remain essential for accurately assessing a company’s financial health and strategic direction in the years to come.
- Investing cash flows also shed light on a company’s capital expenditure policies, highlighting how much is being invested in maintaining or upgrading existing operational facilities and assets.
- Understanding how financing activities work is crucial for any business owner looking to grow and expand their operations effectively.
- By understanding the fundamentals of different property types, analyzing deals carefully, applying suitable financing strategies, and executing disciplined management, investors can tap into the enduring value of commercial property.
This segment shows how a company raises and repays capital through debt and equity financing. In this segment, cash inflows come from issuing stock or borrowing, while cash outflows include loan repayments, dividend payments, and stock buybacks. Raising cash through financing can support expansion, but excessive how to calculate gross profit margin debt without revenue growth may pose risks.
What’s the deal with investing activities in a cash flow statement?
It reveals how cash moves through a business, including operations, investments, and financing activities. The cash flow statement highlights liquidity, showing whether a company can generate enough cash to sustain itself, invest in growth and meet its financial obligations. These financial measures are not measures of financial performance under GAAP and should not be considered as an alternative to net income, earnings per share and cash flows from operations, as defined by GAAP. Capital and operating expenses are two sides of the same coin, each playing a role in business success. Capital expenses represent long-term investments in fixed assets that support future growth while operating expenses focus on the day-to-day costs necessary to ensure continued operations.
Key Takeaways
Operating cash flows represent the cash that a company generates from its normal business operations. This measure is crucial because it indicates the ability of the business to generate sufficient cash to fund its operations, pay its debts, and invest in future growth, independent of external financing sources. Operating cash flows are derived from the core business activities of the company, such as selling products or services, and are a direct reflection of how well the company can convert its operations into cash. This figure is a fundamental component of a company’s cash flow statement, providing insights into the financial health and operational efficiency of the business.
It offers a window into the company’s priorities, whether they are expanding, maintaining, or scaling down operations, which in turn affects the company’s future revenue generation and profitability. The net cash flows from operating activities can be determined using either the direct or indirect method. While companies are mostly allowed to choose any of these two methods worldwide, major accounting frameworks, like GAAPs and IFRSs, suggest the use of the direct method. Because of the misplacement of the transaction, the calculationof free cash flow by outside analysts could be affectedsignificantly. Free cash flow is calculated as cash flow fromoperating activities, reduced by capital expenditures, the valuefor which is normally obtained from the investing section of thestatement of cash flows.
What is the difference between an indirect and a direct cash flow statement
Understanding these bigger-picture trends is essential for timing and strategy. A proforma’s first job is to project how much money the property could realistically bring in, from base rents to ancillary income, minus operating costs. By combining disciplined financial analysis, proactive management, and strategic planning, investors can navigate CRE’s complexities and leverage its unique strengths for sustained, long-term wealth creation. On January 9, 2025, the Company entered into the First Amendment to the 2024 Term Loan Agreement and incurred $63.0 million of Incremental Term Loans (the “2024 Amended Term Loan Agreement”), resulting in total outstanding borrowings of $225.0 million. By understanding how these three areas interact with each other companies can make informed decisions about their finances leading them towards success over time. One example of investing activity is when a company buys new machinery to improve its production process or expands its facilities by purchasing additional land or buildings.
Investing activities are a crucial part of understanding a company’s cash flow. These activities involve the purchase and sale of long-term assets, such as property, plant and equipment, and investments in other companies. A statement showing flows of cash & cash equivalent during a specified time period is known as a Cash Flow Statement. Simply put, a cash flow statement is a summary of different sources and applications of cash during a specific time period and analyses the reasons behind changes in cash balance between the two balance sheet dates. (Here, ‘cash’ means cash & cash equivalent) Hence, one can prepare a cash flow statement if the two comparative balance sheets of a company are given. This is the reason why a cash flow statement is also known as Statement of Changes in Financial Position – Cash Basis, or a Funds Flow Statement – Cash Basis.
Cash Flow Statement: Operating, Investing & Financing Activities
By studying both macro (national or global) and micro (local) trends, investors can make data-driven decisions about where and when to deploy capital. Staying on top of economic shifts is vital for investing in commercial real estate, as GDP changes, interest rates, and local job growth directly affect property demand. Whether you’re just exploring investing in commercial real estate or already have a property or two, understanding core principles can dramatically increase your success. By understanding the fundamentals of different property types, analyzing deals carefully, applying suitable financing strategies, and executing disciplined management, investors can tap into the enduring value of commercial property. When equipment is sold for cash, the amount received is reflected as a cash inflow in the cash flow statement. Financing activities cover the ways a company raises capital and repays its debt.
How to Read a Cash Flow Statement and Analyze the Three Types of Cash Flows
Financing Activities will not include Issue of Bonus Shares, Conversion of Debentures into Shares, and Issue of Share Capital, or Debenture against the purchase of fixed assets, as they do not involve cash. Cash under a cash flow statement consists of cash in hand and demand deposits with banks. 3 Operating Fund expenses are the total NCUA operating expenses reduced by the Share Insurance Fund allocation as determined by the overhead transfer rate. Beyond standard commercial loans, various government-backed and niche programs exist to help investors purchase or develop properties with more favorable terms. These loans often feature higher down payments and more rigorous underwriting compared to residential mortgages. Broad economic forces—from GDP growth to interest rate shifts—can set the tone for the commercial real estate market nationwide.
Operating Activities
Cash flows from investing the ultimate guide to pricing strategies activities are cash business transactions related to a business’ investments in long-term assets. They can usually be identified from changes in the Fixed Assets section of the long-term assets section of the balance sheet. Some examples of investing cash flows are payments for the purchase of land, buildings, equipment, and other investment assets and cash receipts from the sale of land, buildings, equipment, and other investment assets.
Commercial properties can be evaluated in several ways, from comparing local sales to factoring in future cash flows. In commercial real estate, certain metrics serve as the backbone of investment analysis, valuation, and risk management. Understanding how to calculate and interpret figures like NOI, Cap Rate, DSCR, and IRR helps investors compare properties, forecast returns, and make better-informed decisions.
What Is Bill and Hold? Conditions, Revenue, and Tax Implications
While ASC 606 governs revenue recognition for financial reporting, tax authorities may use different criteria. Internal Revenue Code (IRC), revenue is generally taxable when earned and realizable. In a bill and hold scenario, this might mean revenue is taxable at the point of billing, even if goods remain with the seller.
Tax authorities, such as the IRS, closely scrutinize these arrangements due to the potential for deferring income or manipulating taxable revenue. Businesses must align tax reporting with the transaction’s economic substance and applicable tax codes. If the seller is responsible for packaging or customizing the goods before delivery, revenue cannot be recognized until these tasks are completed. This prevents premature recognition and ensures financial reporting reflects the economic substance of the transaction. Explore the nuances of bill and hold arrangements, including revenue recognition, inventory ownership, and tax reporting implications. As a result, Sunbeam reported significant sales, which boosted the company’s stock price.
Sunbeam then recorded these transactions as revenue, even though the goods remained in Sunbeam’s warehouses and the distributors had no immediate need for the products. By prematurely recognizing revenue, Sunbeam artificially inflated its sales figures. This created the illusion of a successful turnaround and drove up the company’s stock price. This software aids in generating invoices, tracking payments, and maintaining accuracy in billing processes. It plays a crucial role in ensuring adherence to accounting standards, regulatory requirements, and ethical business practices in bill and hold scenarios. The Securities and Exchange Commission (SEC) is cautious about bill and hold transactions due to concerns about the timing of revenue recognition.
Additionally, the seller should have no further performance obligations related to the goods, aside from storage, to prevent premature revenue recognition. The bill and hold arrangement may be beneficial for the parties involved, but great care must be taken by both parties to ensure that all of the criteria are met. If the arrangement does not meet all of the stated criteria, there will be no transfer of ownership. This means that revenue can’t be recognized by the seller, and no assets or inventory can be recorded by the buyer related to this transaction.
Include all Performance Obligations in Writing
Company C concludes that Customer A’s request for the bill-and-hold basis is substantive. It also concludes that control of the equipment has transferred to Customer A and that it will recognize revenue on a bill-and-hold basis even though Customer A has not specified a delivery date. They document the buyer’s request for billing and the readiness of the goods for shipment. Maintains communication with the retailer to confirm ongoing commitment to fulfill the bill and hold arrangement. Bill and hold transactions add complexity to tax reporting, requiring careful navigation to meet compliance standards.
Smith & Howard
- Smith & Howard PC is a licensed independent CPA firm that provides attest services to its clients, and Smith & Howard Advisory LLC and its subsidiary entities provide tax and business consulting services to their clients.
- Navigating the regulatory landscape of bill and hold arrangements requires a thorough understanding of the applicable guidelines and standards.
- Bill and hold transactions entail a nuanced approach to revenue recognition where sellers bill customers for goods but delay delivery.
- The amount of revenue recognized should represent the consideration to which the entity or the seller expects to be entitled, according to the Financial Accounting Standards Board (FASB).
- Completed products under bill-and-hold arrangements should be clearly identified as belonging to the customer, ready for physical delivery, and restricted from being used for any other purpose or redirected to another customer.
The entities falling under the Smith & Howard brand are independently owned and are not liable for the services provided by any other entity providing services under the Smith & Howard brand. Our use of the terms “our firm” and “we” and “us” and terms of similar import, denote the alternative practice structure conducted by Smith & Howard PC and Smith & Howard Advisory LLC. A bill and hold arrangement can be illustrated with the example of a company that places an order for a large number of pencils with a vendor. The buyer may want to pay for the order in the current accounting period but not want to take possession of the pencils until a later date, possibly due to the need to clear space for the pencils in a storage area. In this scenario, the seller agrees to process the order, and segregate the pencils to fill the order from the rest of its inventory.
- The buyer must assume the risks and rewards of ownership, even if the seller retains possession.
- It constitutes a sales arrangement in which a seller of a product bills a customer for the product upfront but does not ship the product until a later date.
- This case study showcases how bill and hold arrangements can be used to accommodate customer needs while adhering to revenue recognition principles.
- For more information on revenue accounting and reporting considerations in accordance with Topic 606, including bill-and-hold arrangements, contact your Moss Adams professional.
Baker Tilly Advisory Group, LP and its subsidiary entities provide tax and consulting services to their clients and are not licensed CPA firms. Investment advisory offered through either Moss Adams Wealth Advisors LLC or Baker Tilly Wealth Management, LLC. By maintaining comprehensive documentation, companies can support their revenue recognition decisions and demonstrate compliance with accounting standards. Another example could be a construction equipment manufacturer that receives a large order from a customer for machinery.
Common Challenges in Implementing Bill and Hold Arrangements
Overall, businesses using bill and hold arrangements must prioritize understanding the requirements, documenting the business purpose, exercising caution, regularly reviewing and reassessing, and seeking professional guidance. By doing so, they can navigate the complexities of revenue recognition and ensure compliance with the applicable standards. Bill and hold arrangements are a common practice in revenue recognition, particularly in industries where the timing of product delivery is critical. This arrangement allows a seller to bill a customer for a product, but instead of delivering it immediately, the seller holds the product until the customer is ready to receive it. This can be advantageous for both parties involved, as it allows the seller to recognize revenue while deferring delivery, and the customer to secure inventory without the need for immediate storage. State and local tax implications, particularly sales tax, add another layer of complexity.
The obligation to warehouse the goods on behalf of Customer A represents a separate performance obligation. Company C needs to estimate the stand-alone selling price of the warehousing performance obligation based on its estimate of how long the warehousing service will be provided. The amount of the transaction price allocated to the warehousing obligation is deferred and then recognized over time as the warehousing services are provided. These criteria are essential for ensuring that revenue is recognized appropriately in a bill and hold arrangement. By meeting these criteria, the seller can be confident that they are adhering to the principles of revenue recognition and accurately reflecting the timing of revenue in their financial statements. Bill and hold transactions require detailed documentation to ensure transparency and compliance with accounting standards.
The Criteria for Recognizing Revenue in a Bill and Hold Arrangement
This case study showcases how bill and hold arrangements can be used to accommodate customer needs while adhering to revenue recognition principles. When it comes to accounting for bill and hold arrangements, following best practices is crucial to ensure accurate revenue recognition and compliance with accounting standards. In this section, we will discuss some key practices that can help you properly account for bill and hold arrangements. In conclusion, implementing bill and hold arrangements can present various challenges for companies. From lack of documentation and the risk of obsolescence or damage to increased complexity in revenue recognition, it is essential for businesses to be aware of these challenges and proactively address them. By establishing robust documentation processes, mitigating risks, and having clear policies for revenue allocation, companies can navigate these challenges and ensure accurate revenue recognition in bill and hold arrangements.
These articles are intended to provide general resources for the tax and accounting needs of small businesses and individuals. Service2Client LLC is the author, but is not engaged in rendering specific legal, accounting, financial or professional advice. Service2Client LLC makes no representation that the recommendations of Service2Client LLC will achieve any result. Readers are encouraged to contact a professional regarding the topics in these articles. The images linked to these articles are protected by copyright and should not be copied for any reason.
Companies should also conduct regular reviews and assessments of their bill and hold arrangements to ensure compliance with accounting standards and to identify any potential risks or issues. This can involve performing periodic physical inventory counts at the buyer’s location to verify the existence and condition of the goods. For instance, suppose a company enters into a bill and hold arrangement with a customer. However, due to space constraints, the buyer asks the seller to hold the goods for a month. In this case, revenue recognition should occur when the goods are ready for shipment and the buyer has requested the billing, even though physical transfer is delayed.
Company C bills and collects the nonrefundable transaction price from Customer A and agrees to hold bill and hold arrangement the equipment until Customer A requests delivery. The transaction price includes appropriate consideration for Company C to hold the equipment indefinitely. The equipment is complete and segregated from Company C’s inventory and is ready for shipment. Customer A has requested that the delivery be delayed, with no specified delivery date. XYZ Pharmaceuticals is a pharmaceutical company that develops and sells prescription drugs. In an effort to streamline its distribution process, XYZ Pharmaceuticals enters into a bill and hold arrangement with a distributor.
Another risk is the possibility of obsolescence or damage to the goods while they are being stored at the buyer’s location. If the buyer is unable or unwilling to accept the goods at the agreed-upon future date, the seller may be left with obsolete or damaged inventory, resulting in potential financial losses. Additionally, bill and hold arrangements can help sellers in managing their production and inventory levels more efficiently. By allowing them to store products at the buyer’s location, sellers can reduce warehousing costs and free up valuable space in their own facilities. Firstly, it allows buyers to secure inventory at current prices, even if they don’t have immediate storage capacity or need for the goods.
During this period, the buyer remits payment for the order and the seller records the purchase in the accounting receivables. On the date agreed upon by the two parties, the seller ships the pencils to the address provided by the buyer. Upon receipt of the shipped pencils, the order is considered filled by both parties. Goods producers also must determine if there’s a custodial component during a bill-and-hold arrangement.
Definition, Explanation and Examples

The accounting equation is similar to the format of the balance sheet. While there is no universal definition for liabilities and equity, liabilities are typically external claims (e.g., creditors and suppliers), and equity is internal claims (e.g., business owners and shareholders). It’s called the Balance Sheet (BS) because assets must equal liabilities plus shareholders’ equity. For example, if a company becomes bankrupt, its assets are sold and these funds are used to settle its debts first. Only after debts are settled are shareholders entitled to any of the company’s assets to attempt to recover their investment. The accounting equation is a concise expression of the complex, expanded, and multi-item display of a balance sheet.
Example Transaction #3: Purchase of Supplies on Credit
It can be defined as the total number of dollars that a company would have left if it liquidated all of its assets and paid off all of its liabilities. The 500 year-old accounting system where every transaction is recorded into at least two accounts. Therefore cash (asset) will reduce by $60 to pay the interest (expense) of $60. An asset is cloud computing a resource that is owned or controlled by the company to be used for future benefits.
In this case, Speakers, Inc. uses its cash to buy another asset, so the asset account is decreased from the disbursement of cash and increased by the addition of installation equipment. Owners can increase their ownership share by contributing money to the company or decrease equity by withdrawing company funds. A liability, in its simplest terms, is an amount of money owed to another person or organization.
In other words, this equation allows businesses to determine revenue as well as prepare a statement of retained earnings. This then allows them to predict future profit trends and adjust business practices accordingly. Thus, the accounting equation is an essential step in determining company profitability. Valid financial transactions always result in a balanced accounting equation which is the fundamental characteristic of double entry accounting (i.e., every debit has a corresponding credit).
- The remainder is the shareholders’ equity, which would be returned to them.
- An asset is a resource that is owned or controlled by the company to be used for future benefits.
- However, due to the fact that accounting is kept on a historical basis, the equity is typically not the net worth of the organization.
- The equation is generally written with liabilities appearing before owner’s equity because creditors usually have to be repaid before investors in a bankruptcy.
Alternatively, an increase in an asset account can be matched by an equal decrease in another asset account. It is important to keep the accounting equation in mind when performing journal entries. The shareholders’ equity number is a company’s total assets minus its total liabilities.
Accounting Equation Formula and Calculation
Assets are resources the company owns and can be used for future benefit. Liabilities are anything that the company owes to external parties, such as lenders and suppliers. Stockholders can transfer their ownership of shares to any other investor at any time. Owners’ equity typically refers to partnerships (a business owned by two or more individuals). Economic entities are any organization or business in the financial world.
Company worth
Said a different way, liabilities are creditors’ claims on company assets because this is the amount of assets creditors would own if the company liquidated. It’s important to note that although dividends reduce retained earnings, they are not expenses. Therefore, dividends are excluded when determining net income (revenue – expenses), just like stockholder investments (common and preferred). In accounting, we have different classifications of assets and liabilities because we need to determine how we report them on the balance sheet.

The accounting equation helps to assess whether the business transactions carried out by the company are being accurately reflected in its books and accounts. The balance sheet reports the assets, liabilities, and owner’s (stockholders’) equity at a specific point in time, such as December 31. The balance sheet is also referred to as the Statement of Financial Position. Since the balance sheet is founded on the principles of the accounting equation, this equation can also be said to be responsible for estimating the net worth of an entire company. The fundamental components of the accounting equation include the calculation of both company holdings and company debts; thus, it allows owners to gauge the total value of a firm’s assets. The fundamental accounting equation, also called the balance sheet equation, is the foundation for the double-entry bookkeeping system and the cornerstone of the entire accounting science.
In other words, the shareholders or partners own the remainder of assets once all of the liabilities are paid off. In this case, there is no transaction that can make the equation not balanced. If there is, it would only mean one thing which is there is an error in accounting.
However, each partner generally has unlimited personal liability for any kind of obligation for the business (for example, debts and accidents). Some common partnerships include doctor’s offices, boutique investment banks, and small legal firms. Regardless of how the accounting equation is represented, it is important to remember that the equation must always balance. This number is the sum of total earnings that were not paid to shareholders as dividends.
Liabilities
In this case, the owner’s equity will be replaced with the elements that make it up. Although the balance sheet always balances out, the accounting equation can’t tell investors how well a company is performing. The accounting equation is also called the basic accounting equation or the balance sheet equation. Ted is an entrepreneur who wants to start a company selling speakers for car stereo systems.
In the accounting equation, every transaction will have a debit and credit entry, and the total debits (left side) will equal the total credits (right side). In other words, the accounting equation will always be “in balance”. These elements are basically capital and retained earnings; however, the expanded accounting equation is usually broken down further by replacing the retained earnings part with its elements. This straightforward relationship between assets, liabilities, and equity is considered to be the foundation of the double-entry accounting system. The accounting equation ensures that the balance sheet remains balanced. That is, each entry made on the debit side has a corresponding entry (or coverage) on the credit side.
My Accounting Course is a world-class educational resource developed by experts to simplify accounting, finance, & investment analysis topics, so students and professionals can bookkeeping services lincoln learn and propel their careers. Apple receives $1,300 cash from Harvard for app development services that it has performed. Nabil invests $10,000 cash in Apple in exchange for $10,000 of common stock. Shareholders’ equity comes from corporations dividing their ownership into stock shares. The CFS shows money going into (cash inflow) and out of (cash outflow) a business; it is furthermore separated into operating, investing, and financing activities.
Equity
Cash (asset) will reduce by $10 due to Anushka using the cash belonging to the business to pay for her own personal expense. As this is not really an expense of the business, Anushka is effectively being paid amounts owed to her as the owner of the business (drawings). Required Explain how each of the above transactions impact the accounting equation and illustrate the cumulative effect that they have. In the case of a limited liability company, capital would be referred to as ‘Equity’. However, due to the fact that accounting is kept on a historical basis, the equity is typically not the net worth of the organization.
EDSEL DOPE Once Again Responds To Rumors He Is STATIC-X’s Singer XER0
Either way, if you were planning on catching some of these Static-X reunion shows, this confirmation shouldn’t really stop you. The band is on tour right now with DevilDriver, Dope, Wednesday 13, and Raven Black. Dope continued, saying that if Static-X had hired just a regular old non-costume-wearing vocalist, there would’ve been a shitstorm.
How many editorials have you seen out there trying to figure out who they are? It’s just that natural curiosity to want to know who’s behind the music you like. I don’t think there’s any campaign on trying to “tear down” Static-X either. We’ve covered everything they’ve done since the reunion, and frankly I liked the first Project Regeneration record. I thought it was well done and the songs were great, and I hope the second volume coming up this year is as well.
Both volumes are being worked on by longtime STATIC-X producer Ulrich Wild. In a recent interview with Blabbermouth, Dope opened up about his decision to adopt the name Xer0 and conceal himself in a mask while performing. He also reminisced fondly on his close relationship with late STATIC-X frontman Wayne Static and detailed their shared experience of co-headlining tours in the mid 2010s when he first embarked on solo endeavors. Well, if there was any doubt, you can now lay that doubt to rest. The Danish ‘zine Metal a Day spotted one of Edsel’s tattoos in a photo of ‘Xer0’ performing. So unless some dude has the same exact ink in the same exact spot as the guy who was already rumored to be the Static-X character, this settles it.
“When it came time to put it on stage and take it on tour, it was, ‘There should never be another singer of Static-X that’s a person.” The first of two volumes, “Project Regeneration Vol. 1” featured 12 brand new tracks, containing many of the final vocal performances and musical compositions of Static, along with Campos, Jay and Fukuda. In a new interview with Audio Ink Radio, Edsel Dope said he believes the Xer0 character offers his some privacy and that his moniker in the band should be respected. Dope also mentions that having Xer0 as the frontman for Static-X, and not Edsel Dope or whoever else, allows the band to have a future beyond the iconic Wayne Static. Edsel spoke about his part in honoring Wayne Static’s memory by controlling how his legacy is managed, including the release of Project Regeneration in 2021.
Edsel Dope breaks silence on speculation he is Static-X’s new vocalist
“With STATIC-X, we knew very early on that we were not going to have the overwhelming support of the media and the community,” Edsel continued. Edsel then discussed the role he’s taken on to ensure Wayne Static’s legacy is handled properly, including the 2020 “Project Regeneration” album that consisted of Wayne’s last recordings. “For me, when coming onboard to help complete the last bit of music that Wayne left behind, which ended up accidentally stumbling into what became a treasure trove of content, which I’m so excited and so blessed to have been the guy who got to uncover it,” he said.
Static-X reunited in 2018 with the lineup of original members bassist Tony Campos, guitarist Koichi Fukuda, and drummer Ken Jay alongside new vocalist Xer0. Xer0 is widely believed to be Dope vocalist Edsel Dope, who has spoken at length about his position in the band. Reeder, the visionary behind Metal Addicts, has transformed his lifelong passion for metal into a thriving online community for metal aficionados. As a fervent devotee of black metal, Reeder is captivated by its dark, atmospheric, and often unorthodox soundscapes.
“I feel like as long as we never put another face to STATIC-X, Wayne will always be the face of STATIC-X. It’s appropriate. That was the number one most important thing. I’ll help my friends. This all started in 2014. In 2014, I moved to L.A. I was working on the DRAMA CLUB project and I really, really wanted to produce another band and make a great record without me being in the band. I just wanted to move the controls, do what I do and help another band sound great. I had done it with a couple of other bands that I produced, but I wanted to do it with a band of note. Back in October 2019, a photo was posted online clearly showing that Dope and Xer0 shared the same neck tattoo. However, Edsel later posted a lengthy statement on his band’s Facebook page attempting to quash the rumors, implying Xer0’s distinctive body ink was in fact a Photoshop job. Dope even provided a photograph of himself supposedly observing a STATIC-X performance sidestage to prove he and Xer0 were not the same person. “If it was 25 years ago, we wouldn’t have any of this mess because we’d call the editor of fucking Rolling Stone magazine and go, ‘Hey, dude, we’re gonna let you in on what’s happening,’ and they would go, ‘Oh, this is great,’ and they would get behind it and they would properly help you tell your story to the world. But in the world that we currently live in, that’s not the goal. The goal is, as I said, to be the naysayer and to be the one who lets you in on the fact that there is no Santa Claus and ruins the parade for everybody because they’re just dicks.”
The Top 20 Rock & Metal Releases Of 1995, According To You
Was there ever any doubt that ‘Xer0,’ the highly unsettling Wayne Static cosplayer currently touring with Static-X (tickets), is, in fact, lead Dope dope Edsel Dope? Dope are on every single edsel dope xero one of Static-X’s tour dates, the same way Black Label Society used to be on every Ozzfest. Also, pretending to be Wayne Static every night is probably a nice change of pace from pretending to be a car.
The problem with being a mysterious character in the world of entertainment is if you have a prior history in the world, and recognizable tattoos, it’s very hard to keep your identity a secret. While the identity of Static-X’s new frontman has been rumored to be Edsel Dope, we now have some definitive evidence of his true identity. “And we were always friends, but now we’re like the best of friends. And we owe each other a lot. I’m grateful for the opportunity because without those guys and the years of work they put into building STATIC-X, I wouldn’t have a project to land all those efforts too. And for them, without my efforts to help them survive and exist in the modern day, they would have this band that is no longer around. For lack of a better word, we literally brought STATIC-X back from the dead. And it took allof us to do it.” The group issued five more studio albums before disbanding permanently in June 2013. “You have to understand that if we didn’t make that an absolute mission of ours that people would shit all over it and they would have done everything they could to discredit it. And if it were Edsel Dope singing for Static-X, it would be, ‘Oh, it’s Static Dope.’ Or if it was Burton from Fear Factory, it would be, like, ‘Oh, Static Factory.’ It’s, like, ‘Go fuck yourself.’ You can’t give people the ability to control your narratives or else they’re gonna control it in the worst fucking way possible, because, for whatever reason, that’s the culture that we currently exist in. Brief interjection – writing about Ghost’s lore and writing about the business and creative side of Ghost are two different things.
- Brief interjection – writing about Ghost’s lore and writing about the business and creative side of Ghost are two different things.
- While the identity of Static-X’s new frontman has been rumored to be Edsel Dope, we now have some definitive evidence of his true identity.
- Also, pretending to be Wayne Static every night is probably a nice change of pace from pretending to be a car.
“When it came time to put it on stage and take it on tour, it was, ‘There should never be another singer of Static-X… STATIC-X’s recent tour celebrated the 20th anniversary of the band’s platinum-certified “Wisconsin Death Trip” album and paid homage to Static, who died eight years ago. “It was the first time we cracked the Billboard Top 20. I remember walking into a mall, and there was our record. I couldn’t… I also think that if you put any musician out there in a mask, everyone’s first question is “who is it?” Look at Sleep Token.
EDSEL DOPE Explains Why STATIC-X Couldn’t Just Hire A New Vocalist
Rumors began to swirl that Xer0 was actually Dope frontman Edsel Dope, which have since been confirmed and discussed by Dope himself. Despite everyone knowing the identity of Xer0, Dope still doesn’t want to be known as the guy who fronts Static-X. Campos went on to say that he “knew there would be some negativity” on the Internet once STATIC-X had announced its comeback. “But I think once people heard our story and heard that Wayne’s family had given us their blessing to do what we were doing, and then once they actually saw it, I think that was the big turning point. Once people came out and experienced the show and saw what we were doing, I think it made most of those people turn around.” “Really and truthfully, it’s not so much about it being private as it is about respecting the brand of Static-X and retaining the respect when writing or discussing it. And a good example I can use for that is Ghost. Everybody knows that there’s a dude called Tobias that’s behind the paint, but when people write about Ghost, they don’t call him Tobias; they respect the entity and they call him Papa whatever the fuck he is. And that’s because they respect the creative, they respect the artistic integrity of it enough to honor that.” The first of two volumes, “Project Regeneration Vol. 1” featured 12 brand new tracks, containing many of the final vocal performances and musical compositions of Static, along with bassist Tony Campos, drummer Ken Jay and guitarist Koichi Fukuda.
Lore stories refer to the character, while interviews are always done with Tobias Forge the person. Nobody’s out here changing Xer0’s name to Edsel Dope in stories about tours or any quotes about upcoming bands. But Edsel Dope is certainly talking about Static-X as Edsel Dope, and is referred to as such. Dope is currently touring Europe with Static-X, and will support the nu metal band on the second leg of their North American tour, which kicks off in Austin, Texas November 8. In his statement, Dope also expressed his gratitude at the chance to tour alongside the nu metal band in honour of Wayne Static and Static-X’s album ‘Wisconsin Death Trip’, which marks its 20th anniversary this year. Here’s Edsel in simpler times, offering some logical advice for musicians looking to fund their career by slinging dope, like he did.
In 2018, STATIC-X resurrected and introduced the enigmatic Xer0 as their new frontman. Gossip quickly spread that Xer0 was actually Edsel Dope of DOPE fame–and these rumors have since been validated by Dope himself. Despite this knowledge, however, it seems Edsel is not keen on being recognized for his role in STATIC-X‘s resurgence. Funny enough, this is the second time the mystery member of a prominent band has been identified by an exposed tattoo, after Slipknot’s Alessandro Venturella.
“In many ways, I’m not a big afterlife person, but in this very room, I have felt him tapping me on the shoulder going, ‘Don’t fuck this up, man.’ I have a really great relationship with his family. If there was any pressure, it was self-induced because I try to imagine what it would be like if someone were doing this for me and how much I would want them to care and how much I would want them to make sure it was done right. That was the number one focus. That was where all the energy went. When Erickson noted that social media has given everyone a voice, which in turn has turned out to be more of “negative than a positive”, Dope concurred. “When I got to L.A., the first thing I did was a short West Coast tour with Dope and Wayne Static. I purposely did this because I wanted to reconnect with Wayne and start the conversation with him about — I’m a businessman and energy guy. It made no sense to me that Wayne Static was on tour celebrating the anniversary of Wisconsin Death Trip, playing the album in its entirety as Wayne Static to small crowds. Sadly, even though it’s Wayne Static playing Static-X songs, it’s not the same as Static-X. The amount of people showing up to see Wayne Static was infantile to what would have been if it was Static-X. “Sadly, even though it’s Wayne Static playing STATIC-X songs, it’s not the same as STATIC-X. The amount of people showing up to see Wayne Static was infantile to what would have been if it was STATIC-X.
This album featured some of Wayne‘s final recordings and was a way to commemorate him after he passed away. On October 12, Edsel Dope posted a lengthy statement on his band’s Facebook page quashing the rumours, implying Xer0’s telltale neck tat was in fact a Photoshop job. “I have quietly sat through all of this speculation and have thoroughly enjoyed the ride,” it began. Last week, Static-X fans thought they had identified the reformed band’s mysterious vocalist Xer0 as Edsel Dope – but the frontman of Dope has since quashed those claims, comparing the speculation to “an episode of Scooby-Doo”.
Present Value of an Annuity: Meaning, Formula, and Example

Annuities can be created so payments continue as long as either the annuitant or their spouse is alive if a survivorship benefit is elected. Annuities can also be structured to pay out funds for a fixed period such as 20 years regardless of how long the annuitant lives. As with the present value of an annuity, you can calculate the future value of an annuity by turning to an online calculator, formula, spreadsheet or annuity table.
Annuities
Essentially, in normal interest rate environments, a dollar today is worth more than a dollar tomorrow because it has the ability to earn interest and grow with time. Other riders can be purchased to add a death benefit to the agreement or to accelerate payouts if the annuity holder is diagnosed with a terminal illness. A cost-of-living rider will adjust the annual base cash flows for inflation to correspond with changes in the consumer price index (CPI).
Practical Applications of Annuity Factors
For example, if an individual makes withdrawals before they are 59 ½ years of age, they incur a 10% penalty. They differ in the types of annuities they sell and the fees they charge. Additionally, unlike a traditional 401(k) account, the money you contribute to an annuity doesn’t reduce your taxable income.
Preparing for Financial Health in Your Golden Years: Navigating Cognitive Decline
It uses the discount rate (similar to an interest rate) and the length of time (here represented by the number of payments made) to come up with a constant you can use to derive present and future values. Fixed index annuities with income riders provide guaranteed income and safeguard against market fluctuations, ensuring a reliable income stream during retirement. This combination of security and potential growth makes them a valuable option for retirement planning. An annuity factor is a multiplier that is used to calculate the total amount of money that will be paid out over time under the terms of an annuity contract. The annuity factor is comprised of the interest rate, the number of payments, and the total payment. The calculation reveals the impact of interest growth on your fund over time.
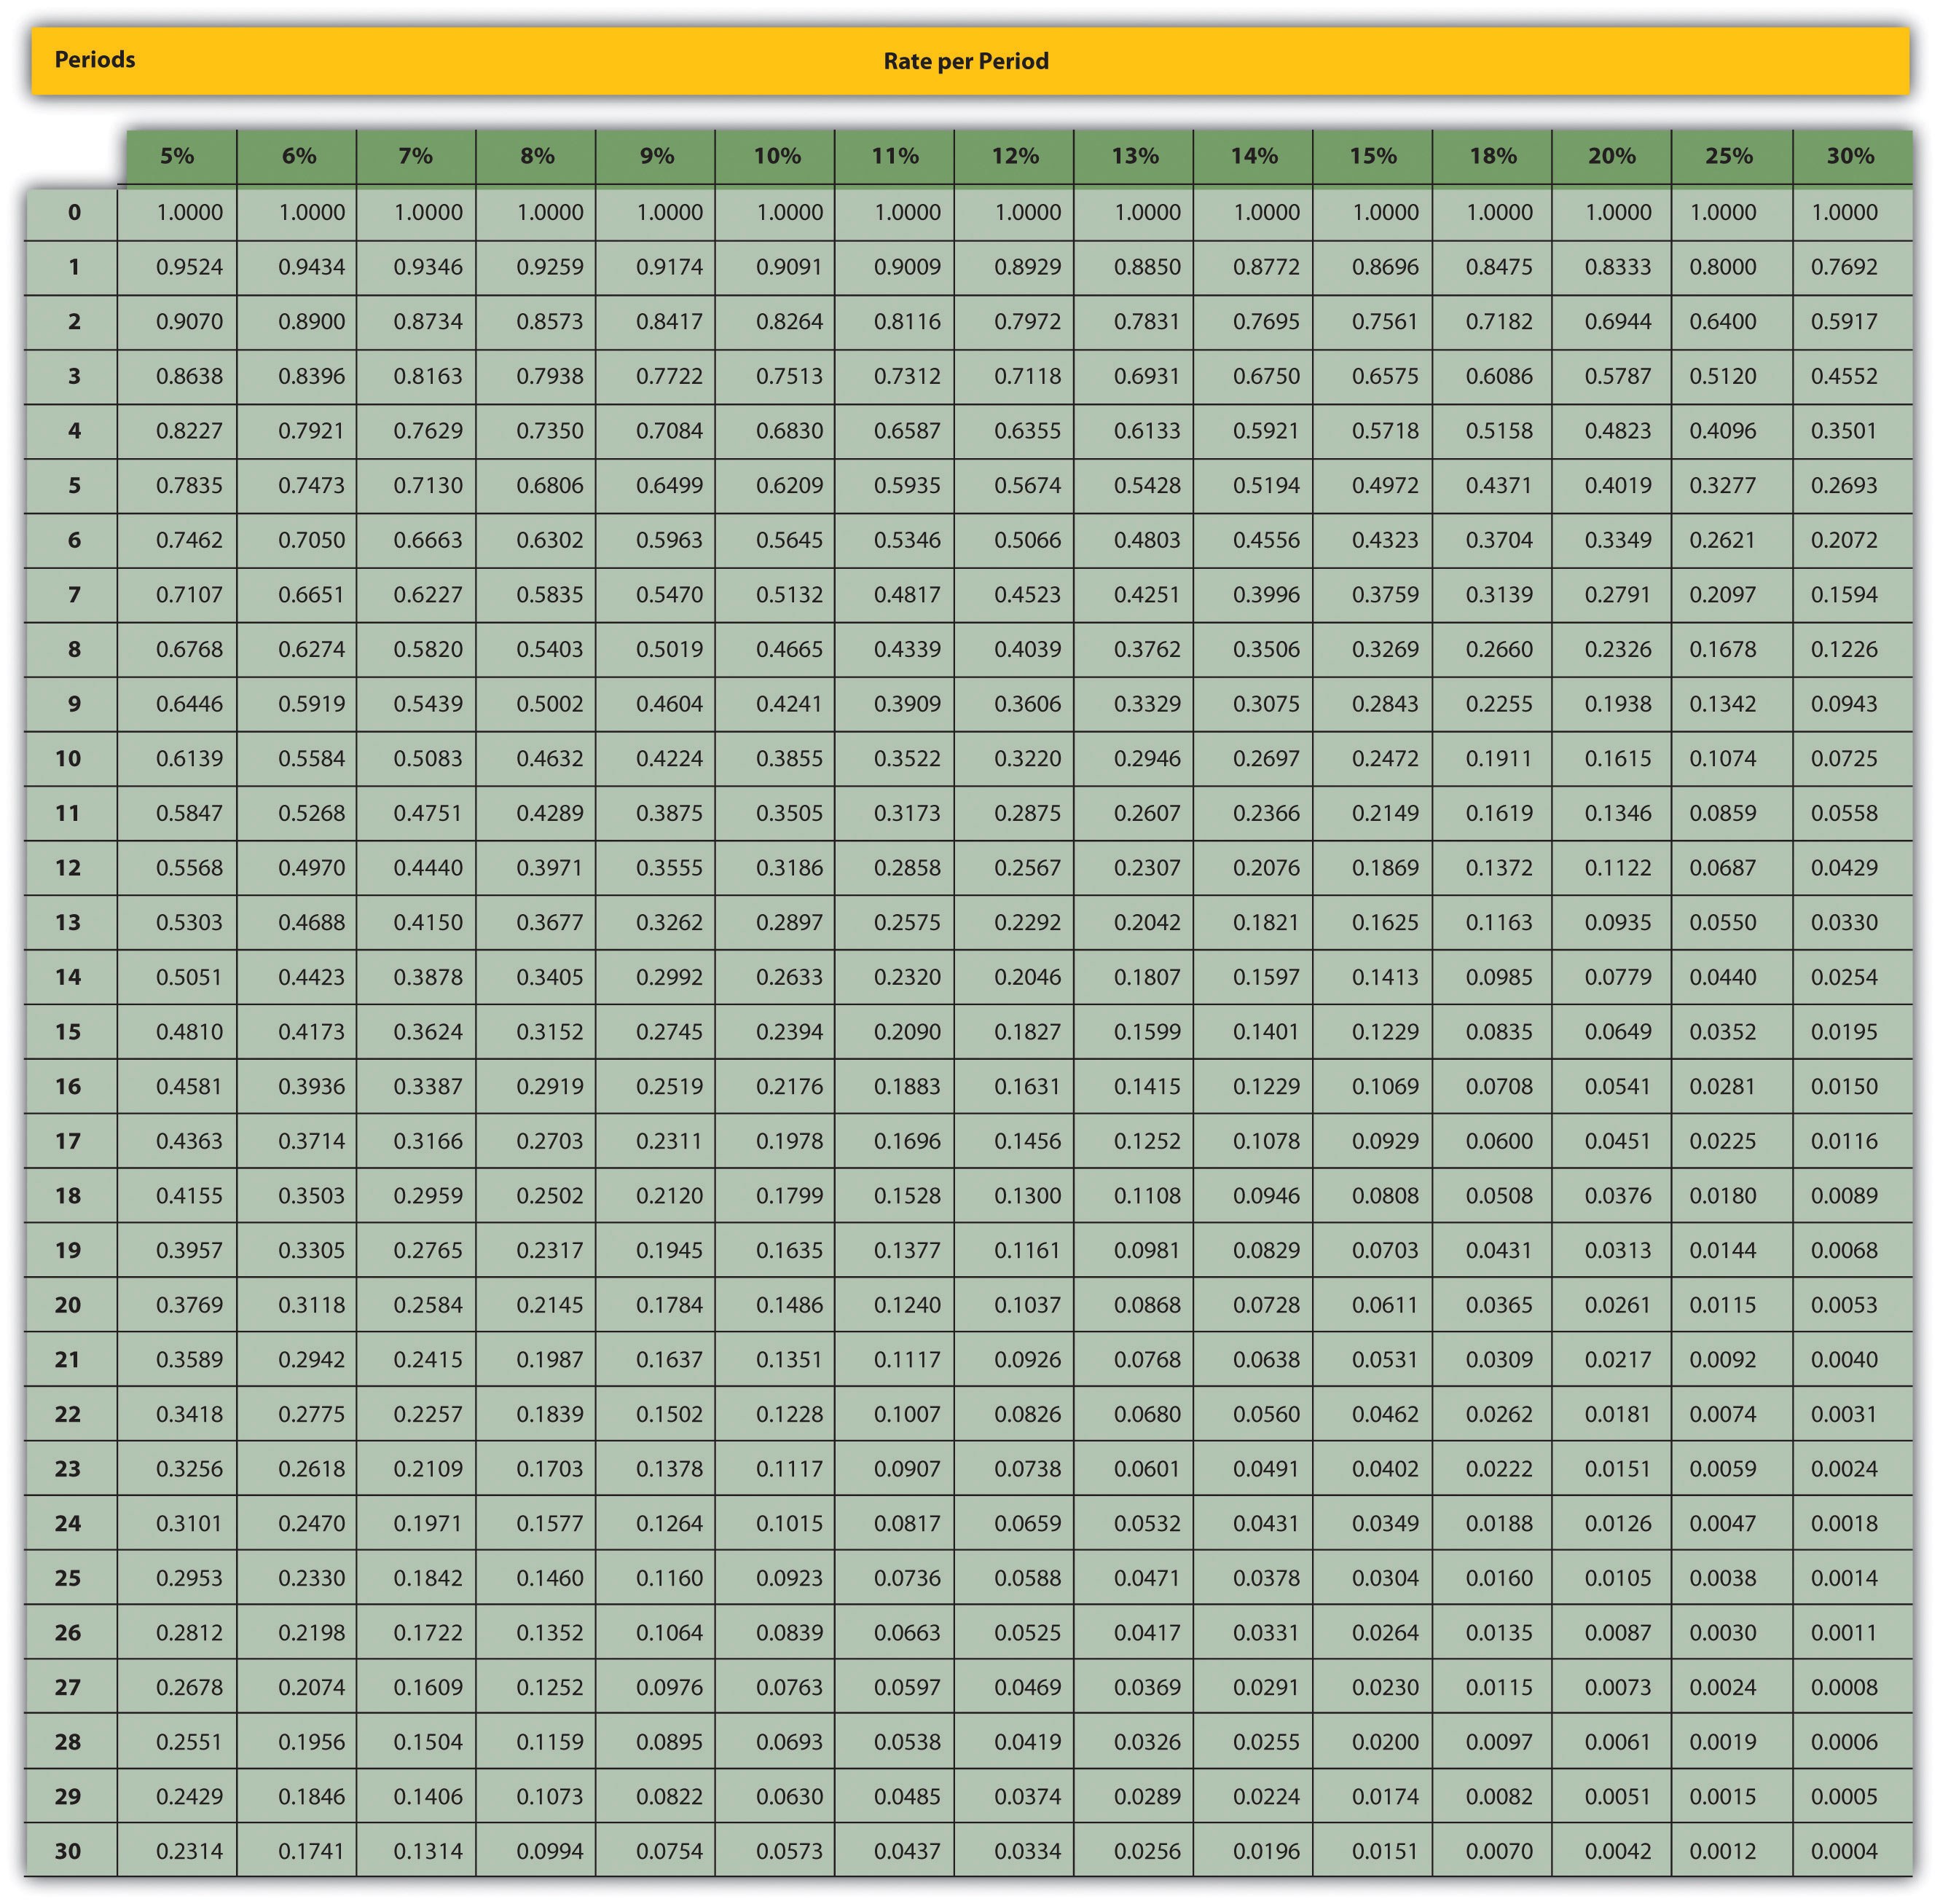
- An annuity table is a tool for determining the present value of an annuity or other structured series of payments.
- Individuals who invest in annuities can’t outlive their income stream and this hedges longevity risk.
- Entering these values in an equation yields the present value of an annuity.
- However, we do not sell annuities or any insurance products, nor do we receive compensation for promoting specific products.
- The annuity factor is a mathematical concept that helps find the present value of a future deposit or withdrawal.
- The definitions and descriptions below apply to the Society of Actuaries Annuity Factor Calculator (AFC).
The discount rate is a key factor in calculating the present value of an annuity. The discount rate is an assumed rate of return or interest rate that is used to determine the present value of future payments. An annuity is a financial product that provides a stream of payments to an individual over a period of time, typically in the form of regular installments. Annuities can be either immediate or deferred, depending on when the payments begin.
Frequently Asked Questions About Annuity Tables
However, you should definitely account for inflation when comparing present and future values. Different types of mortality tables are used depending on the demographic characteristics of the annuity holders, such as age and gender. It is a simple table that features the PVIFAs of common combinations of rates and terms. what is an annuity factor For example, each column might feature a different rate while each row features a different term. Julia Kagan is a financial/consumer journalist and former senior editor, personal finance, of Investopedia. If you die before all the income from an annuity has been paid out, you could receive less than you paid in.
Depending on the type of annuity you buy, your annuitization phase may begin immediately or there may be a surrender period, during which you can’t access the funds without paying a penalty. Landing in the top 10 for annuity sales in 2023, Nationwide netted $4.7 billion in variable annuity premiums alone. It touts over 100 investment options, many of which come with low annual fees and the ability to withdraw up to 10% annually without incurring a penalty.
Today, there’s a wide range of annuities, some of which are less complex and lower in fees and have a range of features that can help you achieve specific financial goals. Click here to sign up for our newsletter to learn more about financial literacy, investing and important consumer financial news. You could find the exact present value of your remaining payments by using a spreadsheet, as shown below. Annuity.org partners with outside experts to ensure we are providing accurate financial content. The rule was set to take effect in September 2024 but has been tied up in litigation as the insurance industry fights back against protections that are expected to significantly limit commissions on annuities. Annuities can be a beneficial part of a retirement plan but they’re complex financial vehicles.
Cash Flow Statement CFS Definition, Calculation, & Example
The Cash Flow Statement (CFS) is essential for assessing a company’s financial health by detailing cash transactions over a specific period. Unlike other financial documents, the CFS focuses exclusively on cash activities, providing a clearer picture of liquidity and cash management. This focus is invaluable for stakeholders seeking to understand how a company generates and uses cash, which can often be a more reliable indicator of stability than net income alone. Cash is the lifeblood of any organization, and a company needs to have a good handle on its cash inflows and outflows in order to stay afloat. As for the balance sheet, the net cash flow reported on the CFS should equal the net change in the various line items reported on the balance sheet. This excludes cash and cash equivalents and non-cash accounts, such as accumulated depreciation and accumulated amortization.
Great! The Financial Professional Will Get Back To You Soon.
It is called the indirect method because the cash flows are not used directly for the calculation, but are determined from the turnover. The sale of company stock for financing can be recorded in this section, along with repurchase of stock, dividend payment, debt repayments (as long as it is for a financing activity). Any payment going out is a negative change, and any payments received are positive changes. In these cases, revenue is recognized when it is earned rather than when it is received. This causes a disconnect between net income and actual cash flow because not all transactions in net income on the income statement involve actual cash items. Therefore, certain items must be reevaluated when calculating cash flow from operations.
For example, rising interest rates might increase borrowing costs, impacting financing cash flows. Similarly, tax code changes affecting depreciation rules could alter operating cash flows. Industry-specific factors, such as seasonal sales in retail, also play a role in shaping cash flow cycles. Cash Flow Statement (CFS) is a pivotal financial document offering insights into the inflows and outflows of cash within an organization.
Understand the significance of CFS in business, its role in assessing financial health, and the methods for analyzing cash flow effectively. This information is helpful so that management can make decisions on where to cut costs. The cash flow statement presents a good overview of the company’s spending because it captures all the cash that comes in and goes out. This is another example of a cash flow statement of Nike, Inc. using the indirect method for the fiscal year ending May 31, 2021. This section records the cash flow between the company, its shareholders, investors, and creditors. Obtaining a certified fund specialist certificate can set analysts apart by giving them an additional certification to show added expertise.
How to Build Cash Flow Statement in Excel
This information allows businesses to forecast future cash needs, make informed investment decisions, and track actual performance against budgeted targets. However, it does not measure the efficiency of the business in comparison to a similar industry. Management can use the information in the statement to decide when to invest or pay off debts because it shows how much cash is available at any given time. Cash-out transactions in CFF happen when dividends are paid, while cash-in transactions occur when the capital is raised.
By studying the CFS, an investor can get a clear picture of how much cash a company generates and gain a solid understanding of the financial well-being of a company. If something has been paid off, then the difference in the value owed from one year to the next has to be subtracted from net income. If there is an amount that is still owed, then any differences will have to be added to net earnings.
What is Cash Flow Statement?
- Assuming the beginning and end of period balance sheets are available, the cash flow statement (CFS) could be put together—even if not explicitly provided—as long as the income statement is also available.
- Note that if there were any dividends issued to shareholders, the amount paid out would come out of retained earnings.
- The cash flow indirect method uses the information from the cash statement to calculate the cash flow within a certain period.
- It produces what is called the net cash flow by breaking down where the changes in the beginning and ending balances came from.
Focusing on net income without looking at the real cash inflows and outflows can be misleading, because accrual-basis profits are easier to manipulate than cash-basis profits. The cash flow statement does not replace the income statement as it only focuses on changes in cash. In contrast, the income statement is important as it provides information about the profitability of a company. This method of calculating cash flow takes more time since you need to track payments and receipts for every cash transaction. As a result, the business has a total of $126,475 in net cash flow at the end of the year.
What are the main components of a cash flow statement?
The net income as shown on the income statement – i.e. the accrual-based “bottom line” – can therefore be a misleading depiction of what is actually occurring to the company’s cash and profitability. Our team of reviewers are established professionals with decades of experience in areas of personal finance and hold many advanced degrees and certifications. However, the cash flow statement also has a few limitations, such as its inability to compare similar industries and its lack of focus on profitability.
For Propensity Company, beginning with net income of $4,340, and reflecting adjustments of $9,500, delivers a net cash flow from operating activities of $13,840. Investing net cash flow includes cash received and cash paid relating to long-term assets. The indirect method, starting with net income and adjusting for noncash items and balance sheet changes, is simpler and more commonly used, especially by larger firms, because it’s efficient and easy to prepare. Therefore, it should always be used in unison with the income statement and balance sheet to get a complete financial overview of the company.
The cash flow statement (CFS), along with the income statement and balance sheet, represent the three core financial statements. A well-prepared CFS highlights operational efficiency by showing cash generated from core business activities. For example, positive cash flow from operations indicates a company can sustain and grow its activities without external financing, reassuring investors and creditors. Conversely, consistent negative cash flow from operations may point to potential issues, such as declining sales or poor cost management, that require attention. Stockholders’ equity transactions, like stock issuance, dividend payments, and treasury stock buybacks are very common financing activities. Debt transactions, such as issuance of bonds payable or notes payable, and the related principal payback of them, are also frequent financing events.
This method is valued for its transparency, linking cash flow data to specific transactions. For instance, a company might report $500,000 in cash received from customers and $300,000 paid to suppliers, giving stakeholders straightforward insights into operational cash flow. Operating activities track cash inflows and outflows tied to core business operations, such as cash received from customers and payments to suppliers and employees. For example, a retail company might report cash inflows from sales and outflows for inventory and payroll.
Cash Flow From Financing Activities (CFF)
The cash flow statement (CFS) shows much more about cash than do other financial statements. Continuing education is also presented by the IBF, which seeks to offer professionals an edge in awareness of contemporary investing tools and market practices. In order to keep up with the requirements, certified fund specialists must complete 30 hours of continuing education every two years. A certified fund specialist (CFS) has received a certification from the Institute of Business & Finance (IBF) for their expertise in mutual funds and the mutual fund industry. Requirements for the designation include passing the certified fund specialist exam. The certified fund specialist exam is one of the oldest certification designations in the mutual fund industry.
Cash from financing activities includes the sources of cash from investors and banks, as well as the way cash is paid to shareholders. This includes any dividends, payments for stock repurchases, and repayment of debt principal (loans) that are made by the company. Investing activities include any sources and uses of cash from a company’s investments.
Our writing and editorial staff are a team of experts holding advanced financial designations and have written for most major financial media publications. Our work has been directly cited by organizations including Entrepreneur, Business Insider, Investopedia, Forbes, CNBC, and many others. The articles and research support cfs finance meaning materials available on this site are educational and are not intended to be investment or tax advice.
A cash flow statement (CFS) is a financial statement primarily intended to provide information about the cash receipts and cash payments of a business during the period of time covered by the income statement. For example, if a customer buys a $500 widget on credit, the revenue is recognized in the month of the sale, even though the cash hasn’t yet been received. The indirect method of presentation is very popular, because the information required for it is relatively easily assembled from the accounts that a business normally maintains in its chart of accounts. The indirect method is less favored by the standard-setting bodies, since it does not give a clear view of how cash flows through a business. For an investment company or a trading portfolio, equity instruments or receipts for the sale of debt and loans are also included because it is counted as a business activity.
Over and Short: Definition and What It Means in Accounting
He has worked as an accountant and consultant for more than 25 years and has built financial models for all types of industries. He has been the CFO market value definition and example or controller of both small and medium sized companies and has run small businesses of his own. He has been a manager and an auditor with Deloitte, a big 4 accountancy firm, and holds a degree from Loughborough University.
Fidelity Smart Money℠
11 Financial’s website is limited to the dissemination of general information pertaining to its advisory services, together with access to additional investment-related information, publications, and taxpayers have more time to file in 2017 links. This voucher indicates the purpose of the expenditure, the date, and the name of the person receiving the cash. In order to clearly understand this cash over and short, let’s go through the examples below.
This discrepancy can occur for a variety of reasons such as errors in counting, theft, or mismanagement of funds. Regardless of the reason, it is important for businesses to understand how to identify and address cash discrepancies to maintain financial stability and prevent losses. In this section, we will explore the different aspects of cash discrepancy, including its definition, causes, and how to prevent it from happening.
In this journal entry, we credit the sales revenue because in the retail business the cash shortage usually happens due to us failing to keep the accurate records that are related to sales revenue. Also, the debit of cash over and short represents the loss, e.g. a few dollars, due to the cash being less than the amount it is supposed to be when comparing the sales records. Likewise, it can save us a bit of time and effort by including both cash shortage and cash overage into only one account. In the realm of financial management, pinpointing and reconciling cash over and short is a nuanced process that begins with the meticulous tracking of daily transactions. This involves comparing the expected what is petty cash and why is it bad for your business cash amounts, based on sales data or receipts, with the actual cash present at the end of a business day.
What is your risk tolerance?
The use of physical cash has decreased due to banking and various online alternatives. However, some companies still use petty cash as a regular part of their activities. This practice may be more common in some industries than others, for example, banking. When handling cash, companies may experience discrepancies in the amount of physical cash and the value recorded in the books. Tracking Cash Over and Short is an important piece of protecting a company’s most valuable asset, Cash, from theft and misuse.
- A firm should note instances of cash variances in a single, easily accessible account.
- Discrepancies in cash handling, known as cash over and short situations, can signal underlying issues that need immediate attention.
- To be sure, adding stocks and bonds to your portfolio doesn’t mean cash has no role to play in your investment strategy.
- If the cash in the register is less than the sales there is said to be a cash shortage.
- This voucher indicates the purpose of the expenditure, the date, and the name of the person receiving the cash.
- Cash Over and Short reconciles what is in the cash drawer vs. what the cash register record says should be in the cash drawer.
- It may seem like a small item to track, but think of it from the point of view of a retail or restaurant chain where millions of dollars pass through the cash registers every day.
Examples of Post-Closing Entries in Accounting
In this case one balance sheet asset (cash), has been increased by 1,414 when the cash is banked. The cash overage/shortage account is an expense account in the income statement of the business. Cash overages are normally recorded in a separate income statement expense account often referred to as the cash over/short account.
Related Terms
In simple terms, Over and Short refers to the variance that arises when the amount counted during a physical count or cash reconciliation doesn’t match the amount recorded in the books. For example, if there are un-reimbursed expenditures from petty cash at the end of the year, expenses are understated and cash overstated. Financial accountants (and independent auditors) are generally not concerned with petty cash because of the immateriality of the amounts. Management should be concerned about controlling the proper use of petty cash. Whatever steps are deemed necessary (such as surprise counts) should be performed to assure that controls are adequate. Another entry to petty cash is not made unless the firm wants to increase or decrease the fund above or below $100.
- This transparency is not merely a matter of regulatory compliance but also a testament to the company’s commitment to financial accuracy.
- Our goal is to deliver the most understandable and comprehensive explanations of financial topics using simple writing complemented by helpful graphics and animation videos.
- Here, you create a new journal entry in your accounting journal and debit, or increase, each expense account by the amount of cash used by your vouchers.
- In the realm of content marketing, whitepapers are a cornerstone, providing in-depth and…
- However, it should be replenished at the end of the accounting period in order to ensure that all expenses are properly recorded.
- Over and short—often called “cash over short”—is an accounting term that signals a discrepancy between a company’s reported figures (from its sales records or receipts) and its audited figures.
Ask Any Financial Question
Furthermore, the physical transfer of cash from point of sale to the safe or bank can introduce variances if not properly monitored and documented. If you’ve stayed in cash because you like how your money market fund makes regular interest payments, you may want to learn more about opportunities in bonds. Unlike cash, they also give you opportunities for capital appreciation and to lock in interest payments that may be higher than what you could earn on cash in the future.
Insights from Fidelity Wealth Management
Cash discrepancy is a common problem that businesses face, and it can have significant effects on their financial stability. When a cash discrepancy occurs, it means that the amount of cash recorded in the books is different from the amount of cash that is actually present. This can happen due to a variety of reasons, such as errors in recording transactions, theft, or fraud. Regardless of the cause, cash discrepancies can have a significant impact on a business’s financial health if not addressed promptly.
Nonprofit Financial Statements: 4 Essential Reports to Know

We can automate your bookkeeping processes, freeing up considerable time for your team. Our expert accounting team can also help you navigate complex tasks such as fund accounting and functional expense reporting, ensuring your books are always audit-ready. You might wonder why it’s referred to as a Statement of Financial Position instead of a Balance Sheet when dealing with nonprofit organizations. Let’s break down each of these pieces to better understand their role and significance in the overall financial health of your nonprofit organization. Among the list of important finance documents your nonprofit organization has to create and use, the statement of financial position is one of the most important.

What’s Included on the Statement of Financial Position?
One such report is the Statement of Functional Expenses, which breaks down expenses by their functional classification. Finally, the net cash flow section summarizes the total cash inflows and outflows from all activities, providing a clear picture of the overall change in cash position during the reporting period. Not-for-profit organizations must file annual information returns with regulatory bodies such as the IRS in the United States. These filings provide detailed information about the organization’s financial activities, governance, and compliance with tax-exempt status requirements, ensuring ongoing eligibility for tax benefits. Another key principle involves the proper allocation of expenses to various programs and administrative activities. Charitable organizations must ensure that they allocate costs accurately to reflect the true nature of their expenditures.

Statement of Activities – A Quick Financial Overview
This rigorous review process, whether internal or external, is crucial for building trust among donors, grantors, and other stakeholders. Nonprofit organizations do not have the same financial reporting https://namesbluff.com/everything-you-should-know-about-accounting-services-for-nonprofit-organizations/ requirements as for-profit businesses. Since nonprofits operate for the purpose of fulfilling their mission instead of distributing profits, financial reporting can get lost in the shuffle.
- One of the key best practices is maintaining transparency in financial statements.
- This difference stems from the fact that each type of organization has separate goals for its balance sheet.
- Reports like Form 990 are public, but internal versions may be shared only with key stakeholders, such as the board or donors.
- Contact Know Your Numbers today for expert guidance and support in mastering the intricacies of financial statements.
- In the context of not-for-profit financial statements, the Statement of Financial Position must adhere to specialized accounting standards.
- This report is essential for understanding how the organization generates revenue and incurs expenses, offering a clear picture of its financial health.
Net assets
Effective record-keeping and systematic organization are paramount, necessitating the use of robust accounting systems accounting services for nonprofit organizations or software tailored for nonprofits. And secondly, if you fail to file a 990 for 3 consecutive years, you’ll automatically lose your tax-exempt status. That means its one financial document every nonprofit needs to be familiar with, even if you’re too small for an audit or struggle to pull together an accurate Statement of Activities every quarter.

Step 3: Categorizing Liabilities into Current and Long-term
Managing your statement of financial position manually can be time-consuming and prone to errors. Consider using technology, such as accounting software or financial management tools, to streamline the process and ensure accuracy. Sometimes, what appears to be lessening resources results from your organization using what it has to make improvements and invest in your nonprofit’s future.
Solved: How do I amend my already filed tax returns to include 1040NR form?
In Part II of Form 1040-X, you should state “Changing the filing status” as a reason for amending your Form 1040 or 1040-SR. If you use Form 1040-X, see the special instructions for carryback claims in these instructions under Special Situations, later. File Form 1040-X for each tax year to which an NOL, a capital loss carryback, a credit carryback, or a foreign tax credit is carried. Write or type “Carryback Claim” at the top of page 1.
Payroll, compensation, pension & benefits
Don’t file Form 1040-X if you are requesting only a refund of penalties and interest or an addition to tax that you have already paid. Instead, file Form 843, Claim for Refund and Request for Abatement. Many find the easiest way to figure the entries for Form 1040-X is to first make the changes in the margin of the return they are amending. Use these instructions with both the paper-filed Form 1040-X and the electronically filed Form 1040-X.
For amended 2021 returns, any adjustments to this deduction should be made to your standard deduction amount on line 2. 526 (for the year of the return you are amending) for the definition of what qualifies as a cash contribution and for information on the types of organizations that qualify. 526 (for the year of the return you are amending) for information on whether this deduction is available on your amended return.
- The items that follow give you this specialized information so your amended return can be filed and processed correctly.
- We will figure any interest and include it in your refund.
- For details, see Federally declared disasters and Combat zones and contingency operations, later.
- Parts II and III on e-filed Forms 1040-X have switched to the following.
- If you are amending your return to claim or change a refundable credit, attach the appropriate schedule(s) or form(s).
However, if the result for column C is zero or less, you must enter -0- in column C. You originally reported $21,000 as your adjusted gross income on your 2022 Form 1040. You received another Form W-2 for $500 after you filed your return.
- If your amended return is signed by a representative for you, you must have a power of attorney attached that specifically authorizes the representative to sign your amended return.
- When electronically filing Form 1040-X to amend a Form 1040-NR, complete Form 1040-X in its entirety.
- Departing Alien Income Tax Return, include on this line the amount you paid as the balance due with that return.
- The period for filing a Form 1040-X to claim or change an election to claim a foreign tax credit or deduction may be extended by an agreement.
- If you received an IP PIN from the IRS, enter it in the IP PIN spaces provided next to the box for your occupation on your Form 1040-X.
What if I miss the filing deadline and file late, or do not file at all?
If you wish to E-File your taxes, you must first confirm that you have not previously E-Filed your tax return before. When you complete the Sprintax questionnaire and proceed through the order breakdown and payment stage, you will be ready to submit your 2024 US tax return. However, when I click on the option that says I already filed 2019 taxes and need an amendment, Sprintax pauses the whole process and tells me that this needs to be treated offline. You should not worry about the penalties and fines if you have no tax liability, the IRS will not penalize you if you do not file a return on time. I tried that, but there is no where to change the filing status.
Form 1040-NR (U.S. Nonresident Alien Income Tax Return) explained and how to file it
On this line, enter the total of the following amounts. Credit for qualifying children and other dependents. Show any negative numbers (losses or decreases) in column A, B, or C in parentheses. Before looking at the instructions for specific lines, the following information may point you in the right direction for completing Form 1040-X. Attach to the back of Form 1040-X any Form 8997, Initial and Annual Statement of Qualified Opportunity Fund (QOF) Investments, that supports changes made on this return if qualified investments were held during the year. Parts II and III on e-filed Forms 1040-X have switched to the following.
Part III—Direct Deposit (for E-Filed Form 1040-X Only)
You are not required to provide the information requested on a form that is subject to the Paperwork Reduction Act unless the form displays a valid OMB control number. Books or records relating to a form or its instructions must be retained as long as their contents may become material in the administration of any Internal Revenue law. Generally, tax returns and return information are confidential, as required by section 6103. If you elected to apply any part of an overpayment on your original return to your next year’s estimated tax, you can’t reverse that election on your amended return. If your original return was changed by the IRS and the result was an additional overpayment of tax, also include that amount on line 18.
However, if you had an extension of time to file (for example, until October 15) but you filed earlier and we received it on July 1, your return is considered filed on July 1. The time limit for filing a claim for credit or refund on a Form 1040-X can be suspended for certain people who are physically or mentally unable to manage their financial affairs. 556, Examination of Returns, Appeal Rights, and Claims for Refund. For additional information, see Schedule 8812 (Form 1040) and its instructions for the year of the tax return you are amending. To file your return electronically, you must sign the return electronically using a personal identification number (PIN) and provide the information described below.
What documents / information might I need to prepare my tax return?
If you are changing the wages paid to an employee for whom you filed Form W-2, you must also file Form W-2c, and Form W-3c, Transmittal of Corrected Wage and Tax Statements, with the Social Security Administration. Under certain circumstances, you may have additional time to file an amended return to claim a refund or credit. For details, see Federally declared disasters and Combat zones and contingency operations, later. The tax filing deadline usually falls on Apr 15 of the following year for which the tax return is being prepared. If Apr 15 is a public holiday or a non-working day, it falls on the next work day. The 2020 tax filing deadline was extended by the IRS to May 17, 2021 due to the COVID pandemic.
You’ll need to sign in or create an account to connect with an expert. A PIN is any combination of five digits you choose except five zeros. If you use a PIN, there is nothing to sign and nothing to mail—not even your Forms W-2. A direct deposit will amended 1040x using sprintax be issued using the banking information on Form 1040-X. Do not complete lines 35b through 35d on Form 1040, 1040-SR, or 1040-NR.


 /wabisabisupplement